
Sandwich Panel Market Analysis by Core Material, Skin Material, and Application
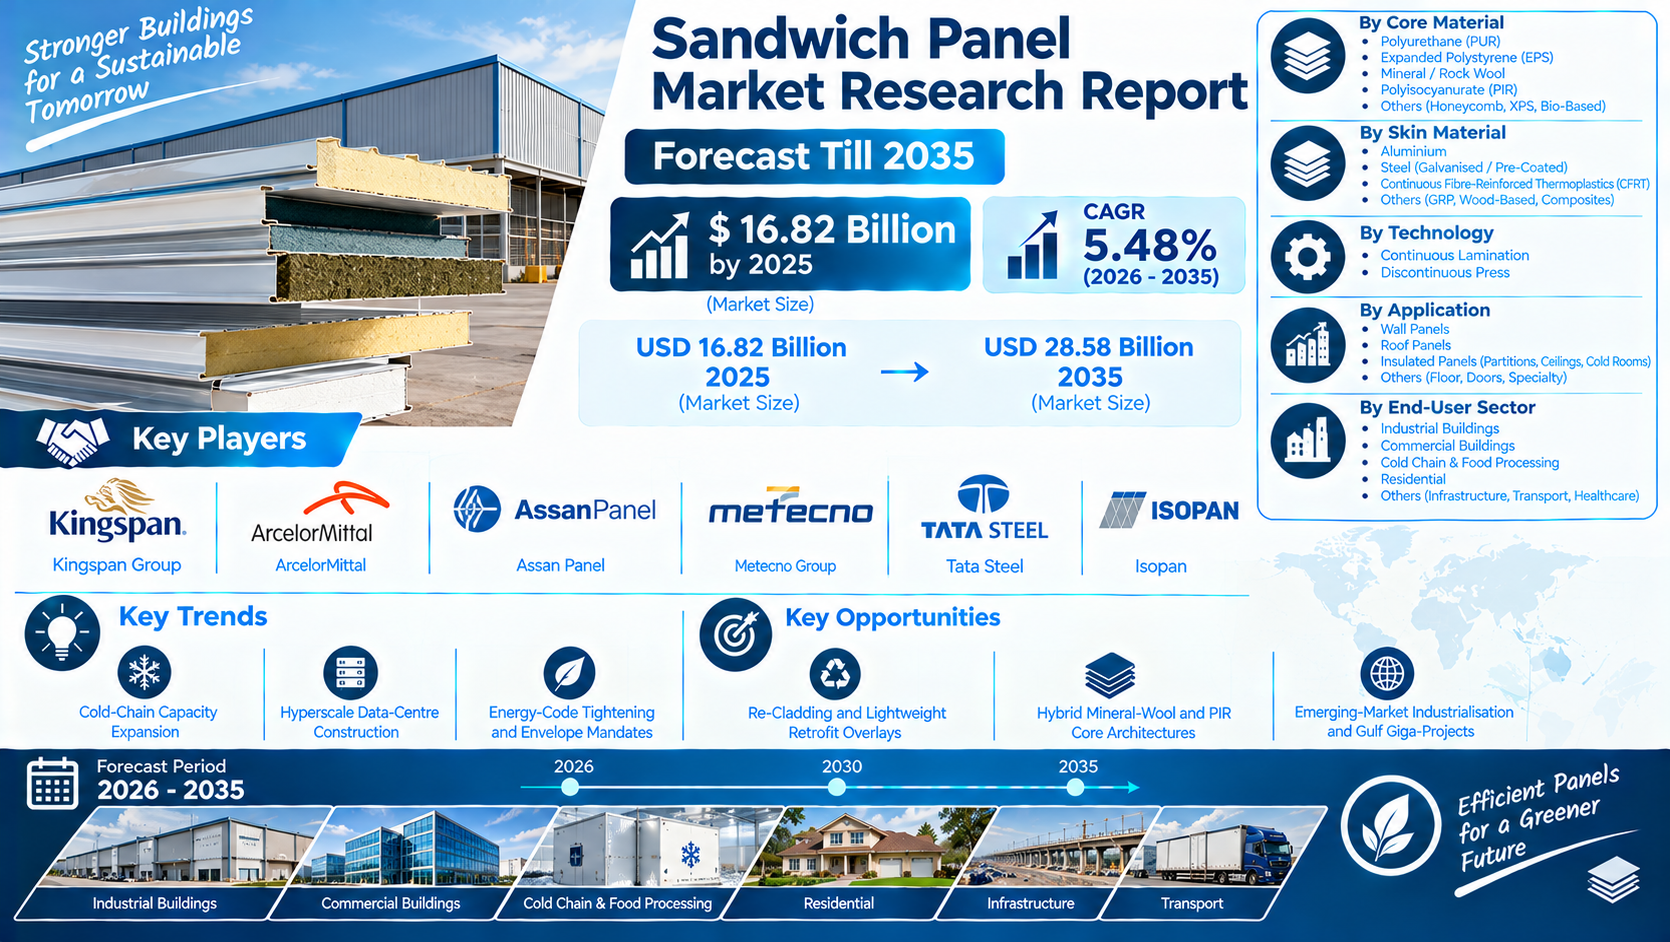
According to Market Research Future® (MRFR), the Sandwich Panel Market is projected to grow from USD 16.82 billion in 2025 to USD 28.58 billion by 2035, registering a compound annual growth rate (CAGR) of 5.48% during the forecast period of 2026–2035. Demand for energy-efficient building envelopes, expanding cold-chain infrastructure, hyperscale data-centre construction, and lightweight retrofit solutions are among the major themes shaping the market outlook.
Sandwich Panel Market Overview
Sandwich panels are composite building components designed with a core material between two outer skins. Their combination of insulation and structural or protective properties makes them suitable for multiple construction applications. Depending on the selected core, skin, and manufacturing technology, panels can serve different thermal, durability, and installation requirements across industrial, commercial, and other building projects.
The market is forecast to increase by USD 11.76 billion between 2025 and 2035, based on the supplied estimates. This expansion reflects potential demand from new construction and building renovation, as well as applications that require controlled indoor conditions. Project specifications, building regulations, material costs, and the suitability of different panel configurations will influence purchasing decisions.
Core and Skin Materials Shape Product Selection
Core material is a major segmentation category, covering polyurethane (PUR), expanded polystyrene (EPS), mineral / rock wool, polyisocyanurate (PIR), and other materials, including honeycomb, XPS, and bio-based options. These alternatives allow buyers to consider different insulation, fire-performance, weight, and application requirements. The most suitable choice depends on the project's technical specifications and applicable building standards.
Skin materials include aluminium, steel (galvanised / pre-coated), continuous fibre-reinforced thermoplastics (CFRT), and other options such as GRP, wood-based materials, and composites. The outer skin contributes to the panel's surface characteristics, durability, and suitability for its operating environment. Selecting an appropriate combination of core and skin is therefore important when balancing performance, installation requirements, and cost.
Technology and Application Segmentation
The report categorizes manufacturing technology into continuous lamination and discontinuous press processes. These production approaches serve as distinct methods for manufacturing sandwich panels, with process selection influenced by product design and manufacturing requirements. Production consistency, panel specifications, and the needs of intended applications are relevant considerations for manufacturers.
Application segments include wall panels, roof panels, insulated panels for partitions, ceilings, and cold rooms, alongside other applications such as floors, doors, and specialty uses. Wall and roof panels support building-envelope construction, while insulated panels are relevant to facilities that need thermal separation or controlled environments. Cold rooms are particularly connected to the wider opportunity in cold-chain infrastructure, where insulation performance can be important to operational requirements.
Key Growth Trends
Three trends highlighted for the market are cold-chain capacity expansion, hyperscale data-centre construction, and tighter energy codes and building-envelope mandates.
Cold-chain expansion creates opportunities for insulated building components in storage and food-processing facilities. As businesses develop infrastructure for temperature-sensitive products, panel solutions can be considered for walls, roofs, partitions, and cold rooms. Actual demand depends on project development, technical specifications, and the performance requirements of each facility.
Hyperscale data-centre construction represents another potential demand source. These facilities require carefully planned building envelopes and supporting infrastructure. Sandwich panels may be considered where their properties align with project requirements, although the supplied information does not quantify their share of data-centre construction spending.
Energy-code tightening and building-envelope requirements can also influence material selection. Building owners and developers may evaluate insulation systems as part of efforts to meet applicable standards and improve building performance. Requirements vary by jurisdiction and project type, so the impact will depend on local regulations and construction practices.
Emerging Opportunities in Construction
Re-cladding and lightweight retrofit overlays are identified as market opportunities. Renovation projects can require upgrades to existing building envelopes, and lightweight systems may be considered when evaluating installation constraints and project needs. The commercial potential of retrofit work depends on building condition, structural considerations, compliance requirements, and the suitability of the chosen panel system.
Hybrid mineral-wool and PIR core architectures offer another area of opportunity. Such configurations may be explored where projects require a balance of insulation and other performance characteristics. Their adoption will depend on design requirements, applicable standards, product availability, and overall project economics.
Emerging-market industrialisation and Gulf giga-projects are also highlighted. Industrial development can create demand for facilities that use insulated construction systems, while large-scale projects may provide opportunities for suppliers capable of meeting project specifications and delivery schedules. The report does not provide a quantified contribution for any of these opportunities.
End-User Sectors and Competitive Landscape
End-user sectors include industrial buildings, commercial buildings, cold chain and food processing, residential construction, and other areas such as infrastructure, transport, and healthcare. Each sector has different requirements for building design, insulation, durability, and installation. This diversity enables manufacturers to serve multiple markets, although demand varies according to investment activity and project specifications.
Key companies identified by MRFR include Kingspan Group, ArcelorMittal, Assan Panel, Metecno Group, Tata Steel, and Isopan. Their participation places the competitive landscape across specialized panel manufacturing and broader materials-related businesses. The supplied data does not provide company market shares or establish a ranking among these players.
Market Outlook Through 2035
The Sandwich Panel Market is projected to reach USD 28.58 billion by 2035, up from USD 16.82 billion in 2025, at a CAGR of 5.48% during 2026–2035. Cold-chain capacity expansion, data-centre construction, building-envelope requirements, retrofit projects, and industrial development are key themes to watch. Manufacturers that align material choices, production capabilities, and product specifications with evolving construction needs may be positioned to pursue opportunities across the market.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)