
Chemical Distributor Market Trends, Opportunities and Competitive Landscape
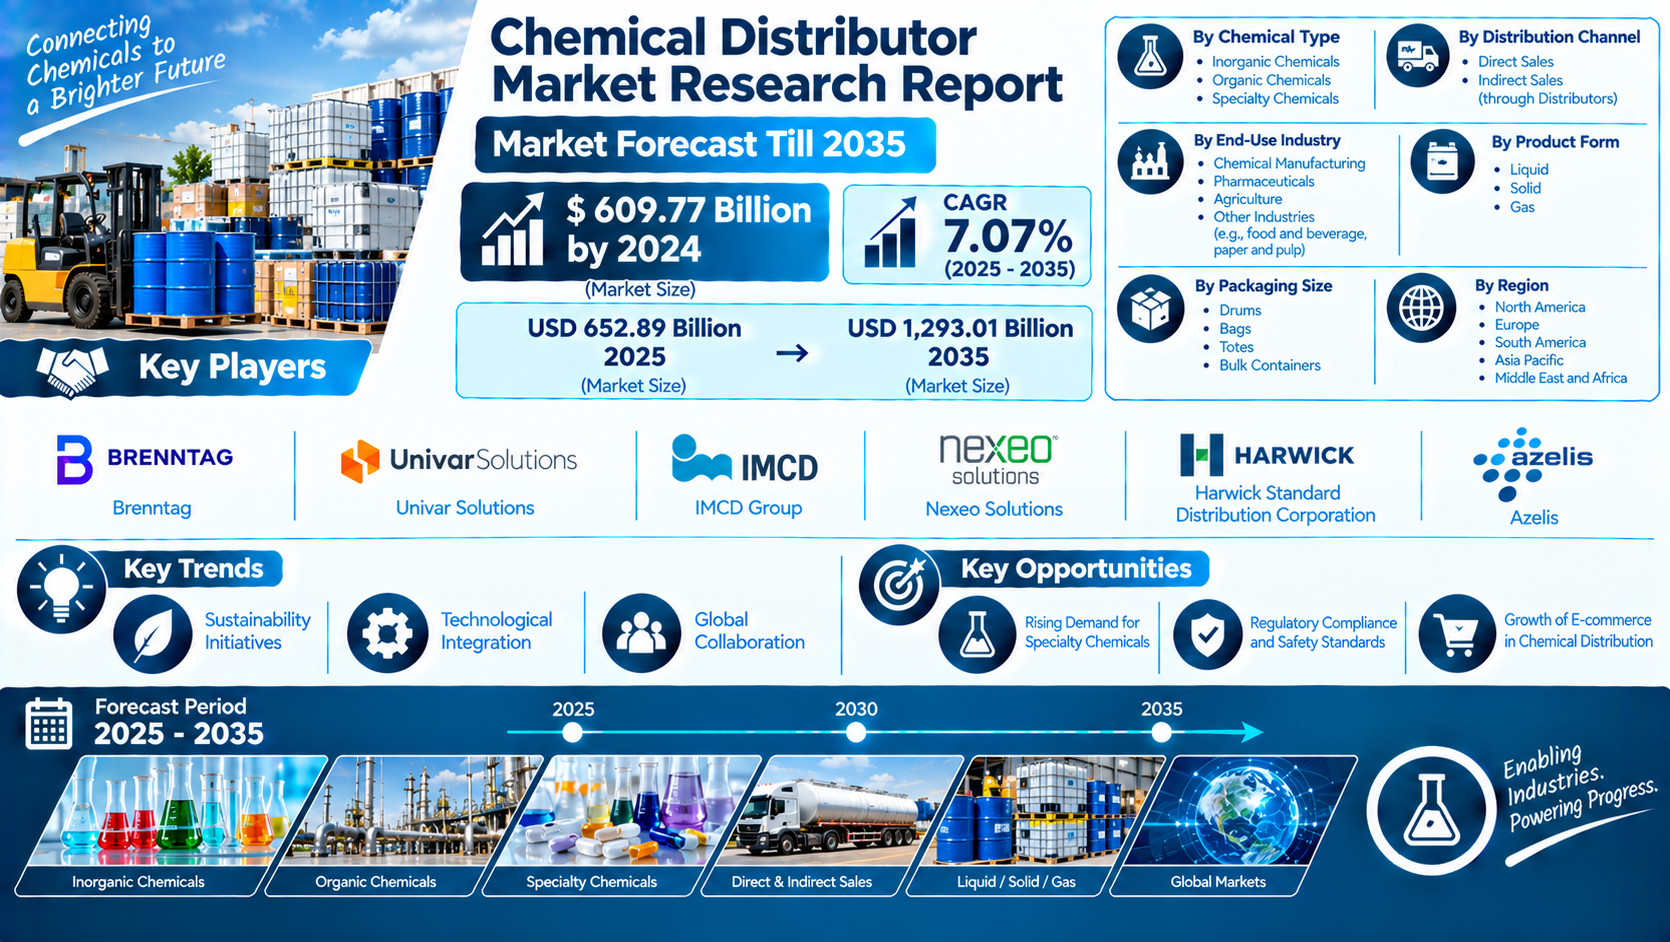
According to Market Research Future® (MRFR), the Chemical Distributor Market was valued at USD 609.77 billion in 2024 and is projected to grow from USD 652.89 billion in 2025 to USD 1,293.01 billion by 2035, registering a compound annual growth rate (CAGR) of 7.07% during the forecast period from 2025 to 2035. Market expansion is supported by demand for specialty chemicals, evolving regulatory and safety requirements, technological integration, and the need for reliable chemical supply chains across manufacturing, pharmaceuticals, agriculture, and other industries.
Chemical Distributor Market Overview
Chemical distributors connect chemical manufacturers with industrial and commercial customers by managing sourcing, storage, packaging, transportation, and product delivery. Beyond moving materials between suppliers and buyers, distributors can provide technical support, inventory management, documentation, and assistance with product selection. These services help customers obtain chemicals in quantities and formats suited to their manufacturing processes.
The distribution sector serves a broad range of industries with different purchasing requirements. Chemical manufacturers need dependable inputs for production, pharmaceutical businesses require materials that meet appropriate quality specifications, and agricultural customers depend on chemicals used in their operations. Food and beverage, paper and pulp, and other industrial sectors add further demand. This diversity makes distribution capabilities, product availability, and regulatory compliance important competitive factors.
The projected increase to USD 1,293.01 billion by 2035 reflects the growing scale and complexity of chemical supply chains. As customers seek reliable sourcing and efficient procurement, distributors can play an important role in connecting producers with end users while helping manage the logistical and administrative requirements of chemical commerce.
Key Market Drivers and Emerging Trends
The rising demand for specialty chemicals is a significant opportunity for distributors. Specialty products are often developed for specific functions or applications, which can require more detailed product knowledge and customer support than standard bulk chemicals. Distributors serving these markets may need to understand technical specifications, handling requirements, and the needs of individual industries.
Regulatory compliance and safety standards also shape market development. Chemicals may be subject to requirements involving classification, labeling, storage, transportation, documentation, and handling. Distributors must understand the rules applicable to their products and operating locations while ensuring that customers receive appropriate information. Compliance capabilities can help reduce operational risk and strengthen relationships with customers and suppliers.
Sustainability initiatives are influencing the way companies assess sourcing and distribution operations. Businesses may seek to improve transport efficiency, reduce packaging waste, optimize inventory, and evaluate products with suitable environmental characteristics. The feasibility of these measures varies according to chemical properties, customer requirements, infrastructure, and applicable regulations. Sustainability can therefore influence both operational planning and supplier selection.
Technological integration is another important trend. Digital inventory systems, electronic ordering, supply-chain visibility tools, and data-driven forecasting can help distributors coordinate stock and respond to customer demand. These capabilities may improve order processing, inventory planning, and communication between suppliers and buyers. Effective implementation depends on data quality, system integration, cybersecurity, and employee adoption.
Market Segmentation by Chemical Type and Channel
By chemical type, the market includes inorganic chemicals, organic chemicals, and specialty chemicals. Inorganic chemicals serve numerous industrial processes, while organic chemicals support applications across manufacturing and other sectors. Specialty chemicals address more specific performance or formulation requirements. Demand across these categories depends on downstream production levels, product specifications, availability, and pricing.
The distribution-channel segmentation covers direct sales and indirect sales through distributors. Direct sales allow manufacturers to supply customers through their own commercial arrangements, while indirect distribution provides an intermediary that can coordinate sourcing, inventory, logistics, and customer service. The appropriate model depends on order size, product complexity, geographic coverage, and the support required by the buyer.
Distributors can be particularly valuable when customers purchase multiple products from different manufacturers or require smaller quantities than producers typically supply directly. Consolidating orders and coordinating deliveries can simplify procurement, although service costs and supply arrangements vary by product and customer.
End-Use Industries and Product Formats
The end-use segment includes chemical manufacturing, pharmaceuticals, agriculture, and other industries such as food and beverage and paper and pulp. Chemical manufacturing requires a range of inputs to support production. Pharmaceutical customers may require materials that satisfy stringent quality and documentation requirements. Agricultural demand is linked to products used in relevant agricultural operations, while food and beverage and paper and pulp businesses have their own application-specific chemical needs.
By product form, the market includes liquids, solids, and gases. Each form requires appropriate storage, packaging, transportation, and handling procedures. The market's packaging-size categories include drums, bags, totes, and bulk containers. Packaging selection depends on the material's properties, required quantity, customer facilities, and relevant safety standards. Distributors must match packaging and delivery arrangements to the requirements of the product and its intended use.
Regional Outlook and Competitive Landscape
The market covers North America, Europe, South America, Asia Pacific, and the Middle East and Africa. Regional demand is influenced by industrial activity, manufacturing capacity, pharmaceutical production, agricultural requirements, infrastructure, and regulatory frameworks. Supply-chain development and access to distribution facilities also affect the ability of companies to serve customers efficiently.
Key players identified in the report include Brenntag, Univar Solutions, IMCD Group, Nexeo Solutions, Harwick Standard Distribution Corporation, and Azelis. Competition can involve product range, technical expertise, logistics capabilities, customer service, inventory availability, and compliance management. The supplied information does not establish individual market shares or rankings.
Growth Opportunities Through 2035
The expansion of e-commerce in chemical distribution presents opportunities to simplify product discovery, ordering, and procurement. Digital platforms can support account management and order tracking, although chemical transactions may require additional documentation and safety checks that differ from ordinary online retail. Global collaboration can also help distributors coordinate international sourcing and respond to customers operating across multiple markets.
With a projected CAGR of 7.07%, the Chemical Distributor Market is expected to continue expanding through 2035. Companies that combine reliable supply networks, strong compliance practices, technical support, and effective digital systems may be well positioned to serve increasingly varied customer requirements.

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek