
Europe Aluminum Market Research: Product Segments, Applications and Competitive Landscape
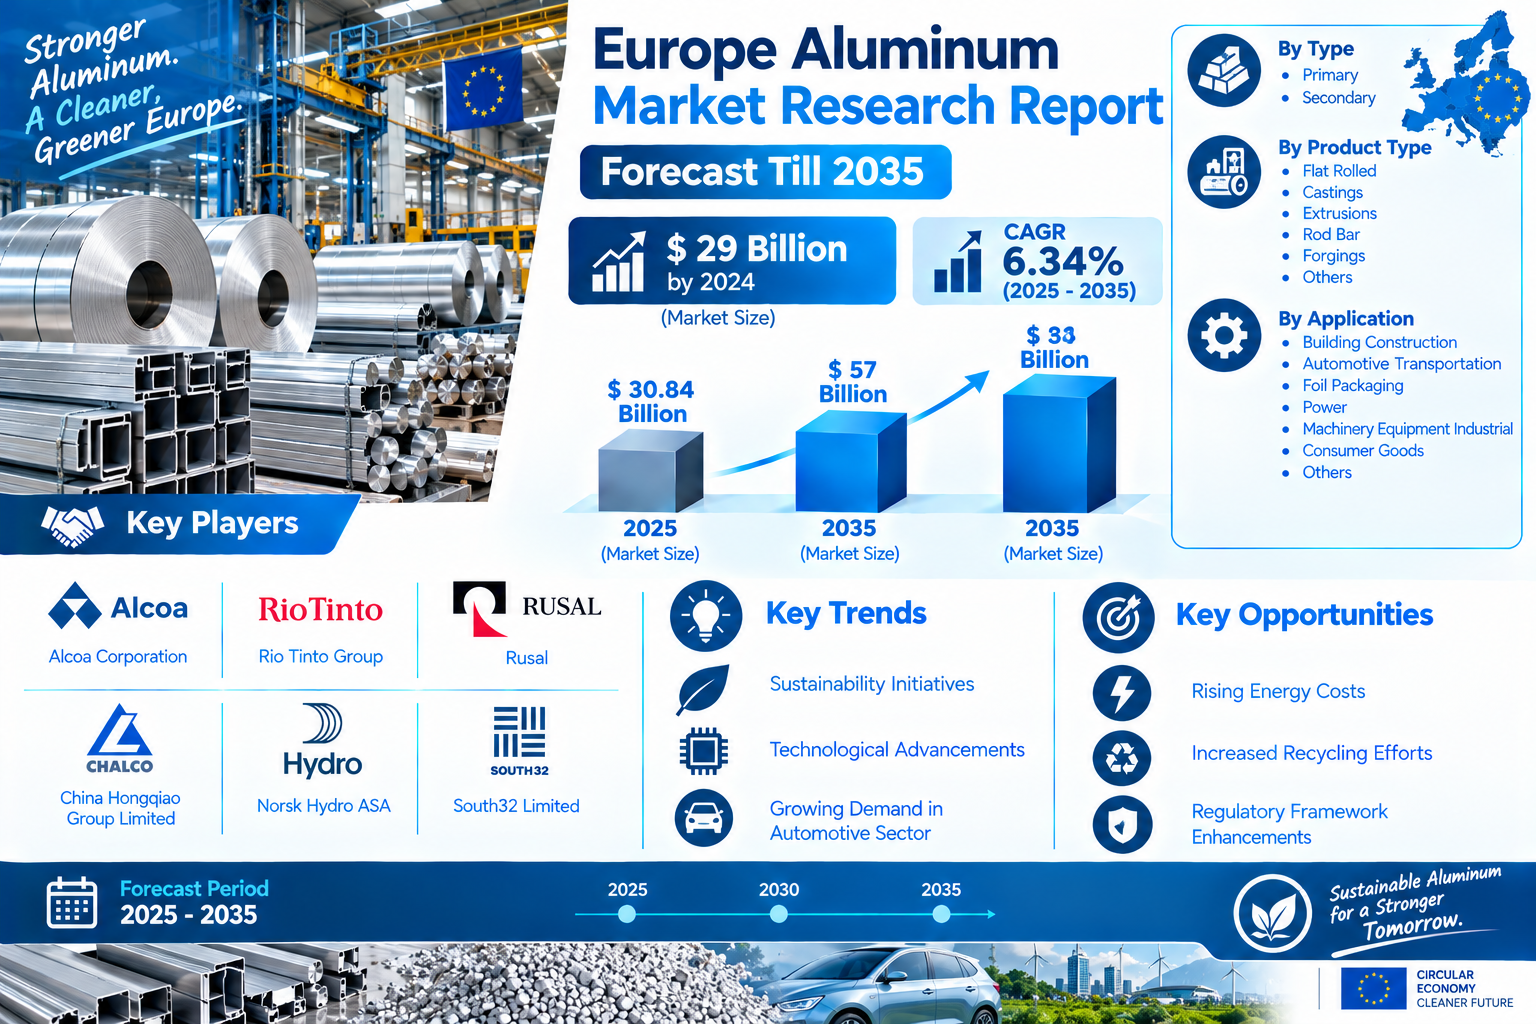
According to Market Research Future® (MRFR), the Europe Aluminum Market is projected to grow from USD 30.84 Billion in 2025 to USD 57 Billion by 2035, registering a compound annual growth rate (CAGR) of 6.34% during the forecast period from 2025 to 2035. The market was valued at USD 29 Billion in 2024. Demand is supported by aluminum's role in construction, automotive manufacturing, packaging, power infrastructure and industrial equipment. Sustainability initiatives, technological advancements and growing automotive-sector demand are among the major trends shaping the industry's development.
Aluminum's Role Across European Industries
Aluminum is widely used in manufacturing because it combines relatively low weight with useful strength, corrosion resistance and recyclability. These characteristics make it suitable for applications in which material performance, durability and weight management influence product design. Across Europe, demand is connected to several industries, including building construction, automotive and transportation, foil packaging, power, machinery and equipment, industrial production and consumer goods.
Construction is an important application area. Aluminum products are used in building components, façades, windows, doors, roofing systems and other architectural applications. Their durability and design flexibility make them relevant to both new construction and renovation projects. Demand can also be influenced by building-efficiency requirements and the need for materials that support modern construction methods.
The automotive and transportation sector represents another important source of consumption. Manufacturers use aluminum in selected vehicle structures, body components, wheels and other parts where reducing weight can support vehicle efficiency and performance objectives. The industry's growing demand for lightweight materials is particularly relevant as manufacturers adapt vehicle platforms and production strategies.
Packaging is another established application. Aluminum foil and related products are used in food, pharmaceutical and other packaging formats because of their barrier properties and ability to protect contents. Power infrastructure and industrial machinery also require aluminum products for applications involving electrical conductivity, fabrication and equipment design.
Primary and Secondary Aluminum Supply
The market is segmented by type into Primary and Secondary aluminum. Primary aluminum is produced from alumina through an electrolytic smelting process. Its production is energy-intensive, making electricity availability and cost important factors in the economics of smelters. Rising energy costs are therefore a significant consideration for producers operating in Europe.
Secondary aluminum is produced by recycling aluminum scrap. Recycling generally requires substantially less energy than producing primary metal from alumina, making it an important part of the industry's resource-efficiency and emissions-reduction strategies. The quality and suitability of recycled metal depend on scrap composition, sorting, contamination control and processing methods.
The relationship between primary and secondary supply is important for the market's long-term development. Primary production provides metal from newly processed raw materials, while recycling recovers value from manufacturing scrap and end-of-life products. Stronger collection systems, improved sorting and more efficient remelting can increase the availability of secondary aluminum. However, recycled material must meet the required chemical composition and performance specifications for its intended application.
Product Types Serve Different Manufacturing Requirements
The Europe Aluminum Market includes Flat Rolled products, Castings, Extrusions, Rod Bar, Forgings and Others. Each product category serves different manufacturing and engineering requirements.
Flat rolled aluminum includes sheet, plate and foil products. These materials are used in transportation, construction, packaging and industrial manufacturing. Their thickness, surface characteristics and mechanical properties can be tailored to specific applications. Demand is influenced by packaging consumption, vehicle manufacturing and the use of fabricated metal components.
Castings are produced by pouring molten aluminum into moulds to create components with defined shapes. They are used in automotive systems, machinery and industrial equipment, where manufacturers require parts with specific geometries. Extrusions are formed by forcing aluminum through a shaped die, allowing the production of profiles used in construction, transportation and industrial applications. Their design flexibility supports applications ranging from structural sections to specialised components.
Rod Bar products are used in electrical, engineering and manufacturing applications, while forgings serve applications that require particular strength and structural properties. The Others category covers additional aluminum product forms included in the report's classification. Product demand depends on downstream manufacturing activity, technical specifications and the ability of suppliers to provide consistent quality.
Sustainability and Recycling Reshape Industry Priorities
Sustainability initiatives are a major trend in the European aluminum industry. Manufacturers and downstream customers are paying greater attention to material sourcing, energy consumption, production emissions and the recovery of aluminum products after use. Aluminum's recyclability supports circular-material strategies, although the environmental performance of a particular product depends on factors such as its production route, electricity mix, transport and recycled content.
Increased recycling efforts present an opportunity for the market. Better collection and sorting systems can help recover aluminum from packaging, vehicles, construction materials and industrial scrap. Advanced separation and remelting technologies can improve the quality and consistency of recycled metal. Manufacturers may also work with customers to improve product design for easier material recovery at the end of a product's useful life.
Regulatory framework enhancements can further influence investment decisions. Requirements and policies related to waste management, emissions, energy efficiency and recycled content may encourage companies to improve production processes and strengthen material traceability. Businesses must monitor applicable rules across European markets because compliance requirements can vary by product and jurisdiction.
Technology and Automotive Demand Support Market Development
Technological advancements are influencing aluminum production, processing and product development. Improvements in casting, extrusion, rolling, surface treatment and recycling can help manufacturers meet increasingly specific customer requirements. Process automation and digital monitoring may also support quality control, production efficiency and material utilisation.
Growing demand in the automotive sector is another significant trend. Vehicle manufacturers are evaluating aluminum components as part of broader efforts to manage vehicle weight and meet performance targets. The transition toward electric vehicles also creates opportunities for aluminum in selected structural and component applications. However, material selection depends on engineering requirements, cost, manufacturing methods and vehicle design rather than weight reduction alone.
The application of aluminum in power infrastructure and machinery equipment provides additional demand channels. Its electrical and fabrication properties make it useful in selected power-related components, while industrial manufacturers use different aluminum forms to produce equipment and engineered parts.
Competitive Landscape and Market Opportunities
The key companies identified in the Europe Aluminum Market include Alcoa Corporation, Rio Tinto Group, Rusal, China Hongqiao Group Limited, Norsk Hydro ASA and South32 Limited. These participants operate within an industry where production costs, raw-material access, energy sourcing, product quality and recycling capabilities influence competitiveness.
Rising energy costs represent a challenge and an opportunity for operational improvement. Energy-intensive primary producers may face pressure on production economics, encouraging attention to efficiency, power procurement and technology upgrades. Increased recycling efforts offer another route to strengthen resource efficiency and expand secondary-metal availability. Regulatory framework enhancements may also create demand for investments in emissions management, traceability and circular production systems.
Europe Aluminum Market Outlook to 2035
The market is forecast to increase from USD 30.84 Billion in 2025 to USD 57 Billion by 2035, with a CAGR of 6.34%. Its expansion will be shaped by demand from construction, automotive and transportation, foil packaging, power, machinery and equipment, and consumer goods.
The balance between primary and secondary aluminum will remain important as manufacturers address supply requirements, energy costs and sustainability objectives. Advances in processing technology and stronger recycling systems may influence product availability and production efficiency. Companies that combine reliable supply, suitable product capabilities and effective resource management will be positioned to participate in the European aluminum industry's projected growth.

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek